 QuickEstimate Team
Construction Overhead: Hidden Costs That Reduce Project Profitability
These challenges are covered in depth in the complete
Estimation Problems Guide →
Getting the construction overhead percentage right is one of the most overlooked parts of project estimation.
Many construction businesses focus only on labor and materials while ignoring
the indirect costs that silently reduce profit margins and create costly financial pressure.
What is Construction Overhead?
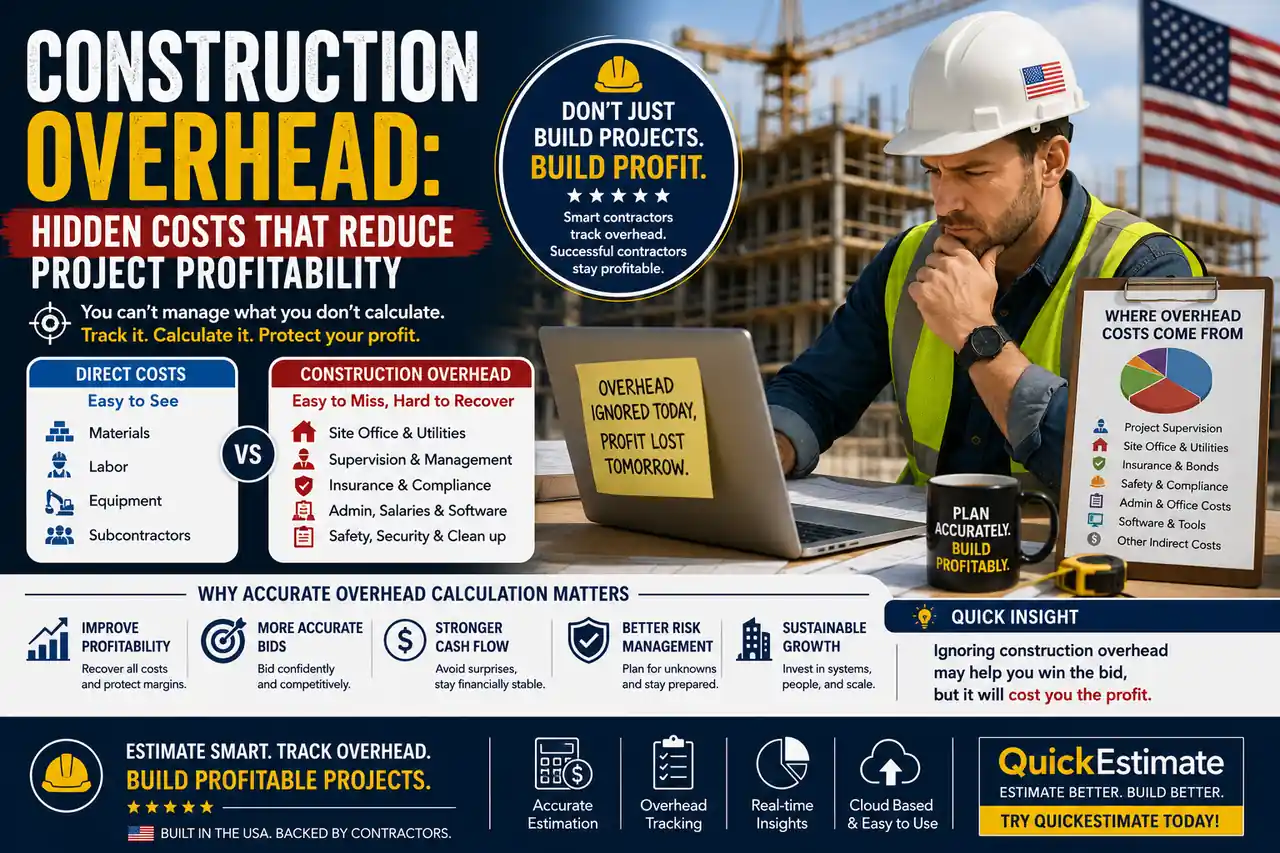
Construction overhead includes all indirect costs required to run a construction project
or operate a construction business successfully. These expenses are not directly tied to physical construction activities
but remain essential for project execution and long-term business continuity.
Without properly calculating construction overhead,
project estimates may appear profitable while actually creating hidden financial losses.
Unlike direct costs such as:
- Materials
- Labor
- Equipment
- Subcontractors
Construction overhead supports operations behind the scenes, including:
- Office rent
- Project supervision
- Temporary utilities
- Insurance costs
- Software subscriptions
- Administrative salaries
- Safety compliance expenses
Types of Construction Overhead
Construction overhead is generally divided into two major categories:
project overhead and company overhead.
Project Overhead
Project overhead includes indirect costs related specifically to a single construction project.
These expenses only exist while the project remains active.
Company Overhead
Company overhead refers to operational expenses required to run the construction business overall,
regardless of active project volume.
Common Project Overhead Expenses
- Site office setup
- Temporary utilities
- Site supervision
- Security and safety
- Temporary fencing
- Cleaning and waste management
- Inspection and permit costs
Common Company Overhead Costs
- Office rent and utilities
- Administrative salaries
- Insurance costs
- Legal and accounting services
- Software subscriptions
- Marketing expenses
- Vehicle and transportation costs
Direct Costs vs Construction Overhead
Understanding the difference between direct costs and construction overhead
is essential for accurate project estimation.
| Category | Examples | Purpose |
|---|---|---|
| Direct Costs | Concrete, labor, steel, equipment rental | Directly tied to construction activities |
| Construction Overhead | Insurance, supervision, office expenses | Supports operations indirectly |
How to Calculate Overhead Percentage
Overhead percentage is always measured against a base, and the base you choose changes the number. Benchmarks published by the National Association of Home Builders are a useful reference point, but check which base they use before comparing. The two most common bases are:
Overhead % of revenue = (Annual Overhead ÷ Annual Revenue) × 100
Overhead rate on job costs = (Annual Overhead ÷ Annual Job Costs) × 100
Example calculation:
- Annual revenue = $500,000
- Annual overhead = $50,000, which is 10% of revenue
- Annual materials and labor = $350,000, so the same overhead is 14.3% of job costs
Same overhead, two different percentages. What matters is using the percentage that matches the costs you add it to when you price a job.
How to Calculate Your Construction Overhead Rate
To add overhead to an estimate, you need it as a percentage of the job costs you add it to. Most contractors use materials and labor as that base, because subcontractors and equipment are usually priced with their own markup.
Overhead Rate = (Annual Overhead Costs ÷ Annual Materials and Labor Costs) × 100
Example calculation:
- Annual overhead costs (office, insurance, vehicles, admin salaries, software) = $120,000
- Annual materials and labor costs = $600,000
- Overhead rate = $120,000 ÷ $600,000 = 20%
- On a job with $40,000 of materials and labor, add $8,000 to cover overhead
Don’t add a percent-of-revenue figure to job costs. It is always lower than the rate on job costs, so part of your overhead goes unpaid on every job. In QuickEstimate, the Overhead % in Business Settings is added to each estimate’s materials and labor, so enter the materials-and-labor rate there.
To work out your own rate, add up a full year of overhead with the free construction overhead calculator and use its “% of materials + labor” result, then use the markup calculator to add profit on top.
Why Contractors Often Underestimate Construction Overhead Percentage
Many contractors focus heavily on winning projects
and unintentionally ignore operational expenses.
Common reasons include:
- Fear of losing bids
- Poor expense tracking
- Manual estimation methods
- Lack of financial planning
- Competitive market pressure
Ignoring construction overhead leads to underpriced projects,
shrinking profit margins, cash flow pressure, and long-term business instability.
How to Control Construction Overhead Effectively
Businesses that properly calculate and manage construction overhead
create more accurate estimates and protect long-term profitability.
Track All Operational Expenses
Monitor utilities, software, insurance, administration,
fuel costs, and every indirect operational expense.
Use Digital Estimation Systems
Construction estimation software improves visibility,
reduces manual errors, and applies overhead consistently.
Standardize Overhead Allocation
Apply overhead consistently across all projects
instead of estimating randomly.
Improve Project Scheduling
Delays increase supervision, utility, and administrative costs.
Efficient scheduling reduces overhead pressure.
Overhead is only one part of the true cost of a job. To see what each employee really costs you per hour, including payroll taxes, benefits and workers’ comp, try our free employee cost calculator.
Frequently Asked Questions
Construction overhead includes indirect operational costs such as supervision,
office expenses, insurance, utilities, software, and administrative support.
Proper overhead calculation protects profit margins,
improves project pricing accuracy, and reduces financial risk.
Ignoring construction overhead leads to underpriced projects,
cash flow problems, reduced profitability, and long-term operational stress.